Money and Reporting Overview
This page explains how money moves for in-store card transactions processed through Verifone and Braintree. It gives product, finance, and operations teams a shared view of authorizations, settlements, disbursements, and fees so they can design processes and reports that line up with how funds flow.
For report details and reconciliation workflows, see the Reporting and Reconciliation Guide and Reports and Analytics Guide.
How in-store transactions move through Braintree
In-store card payments follow the same basic lifecycle as your ecommerce transactions: authorization at the time of purchase, settlement when the transaction is captured, and disbursement when funds are paid out to your bank account. Verifone terminals send card transactions to your Braintree gateway, so in-store and online volume share a common backend and appear together in Braintree reporting.
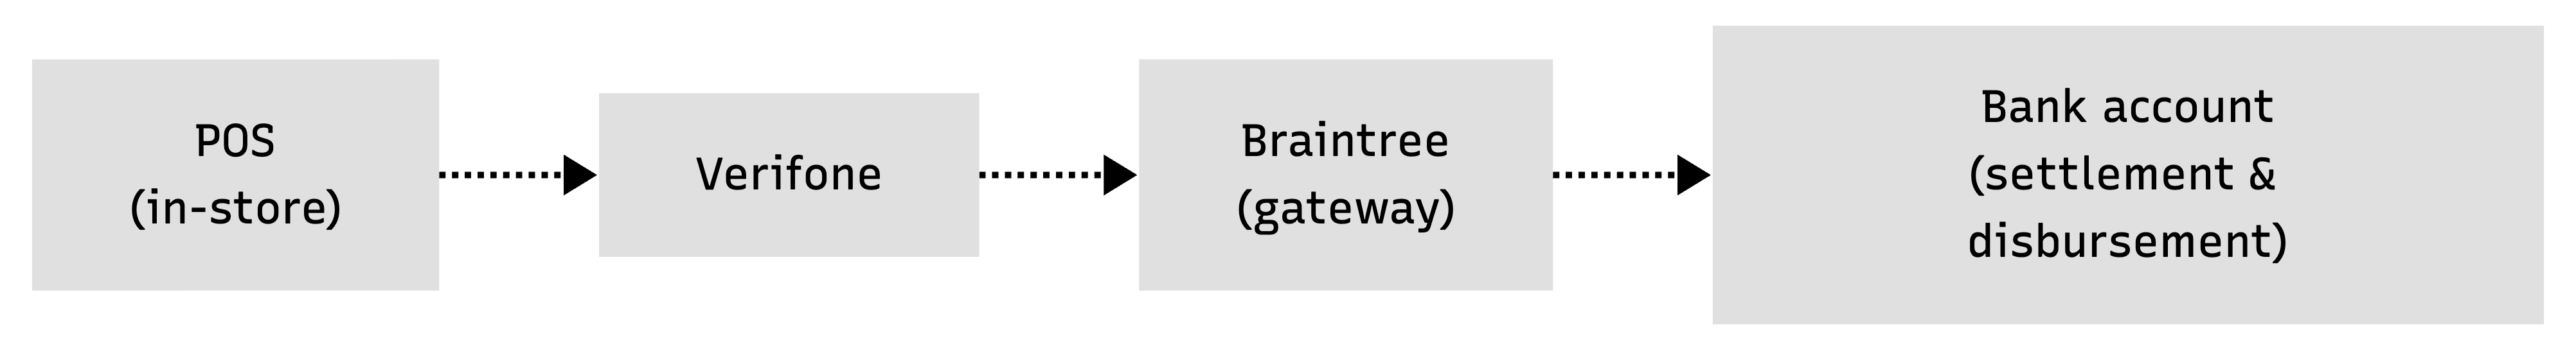
- POS starts the in-store transaction.
- Verifone collects card data and routes the payment.
- Braintree authorizes and settles the card transaction.
- Funds are disbursed to your bank account.
Authorization and capture
At the point of sale, Verifone sends an authorization request to Braintree to confirm that funds are available on the customer's card. Depending on your flow, the transaction is either captured immediately (sale) or later (pre-auth and completion), but in both cases Braintree ultimately submits the captured transaction to the card networks for settlement.
Settlement and disbursement
After payment capture, card networks settle funds to Braintree, and Braintree then disburses those funds to your bank account on a schedule defined in your merchant agreement. In practice, many merchants see a "T+X" pattern, where funds from a given day's settled transactions arrive a small number of business days later, though timing can vary by scheme and region.
How Verifone and Braintree share responsibilities
Verifone is responsible for collecting card or wallet data in store, handling terminal logic, and routing in-store card traffic to your Braintree gateway. Braintree is responsible for processing card authorizations, managing settlement and disbursement, and providing a unified reporting surface that includes both ecommerce and in-store card transactions.
Card payments versus other tenders
Standard credit and debit card payments, along with supported digital wallets, are routed through Braintree and show up in Braintree's transaction and settlement reports alongside your online card volume. Other tenders such as gift cards, private label credit cards, and certain bill payment methods are processed directly on Verifone rails but can still appear in your reporting views, so your teams see a complete picture of in-store activity even when funds settle outside Braintree.
How fees are applied
Braintree applies processing fees to card transactions according to your commercial agreement, typically at or before disbursement, so the amount you receive is net of those fees. From a reporting perspective, you can view gross transaction amounts in your transaction reports and compare them to disbursement and fee reporting to understand your net settlement position.
How this relates to reporting pages
This overview is meant to give you a conceptual model of how money moves, not a step-by-step reconciliation process. For detailed guidance on which reports to run, how to match Braintree data to your POS or Verifone reports, and how to handle timing differences between transactions and payouts, use the Reporting And Reconciliation Guide and the Reports And Analytics Guide pages linked from this section.
AMEX settlement considerations
If you use American Express with your own settlement entity or direct AMEX relationship, AMEX transactions may follow different settlement and funding timelines than other card brands. In these setups, AMEX can disburse funds directly to you instead of through Braintree, so your finance and operations teams should account for separate AMEX statements and payout schedules when performing reconciliation.